Archive for September, 2010

by Gleb Lerman, The Affordable Oracle

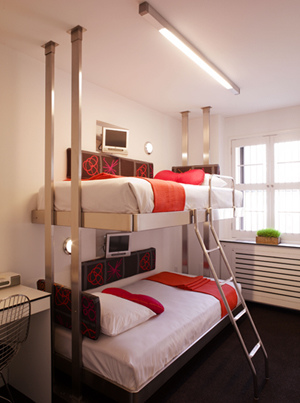
We have all heard the saying before, to succeed you have to be different. I stumbled on an article over at elitechoice.org about the Pod Hotel which has small 50SF rooms with bunk beds. It seems to be a hybrid between a traditional budget hotel and a hostel which may be different enough to succeed. Check out the efficiency of space utilization in this room:

source: flicker.com

One of the greatest challenges for the real estate appraiser (analyst, investor, etc.) is estimating stabilized real estate taxes. RE taxes are almost always the largest expense category for an income property and trying to understand the assessor’s thinking is always a challenge. For many properties, the real estate tax is a non-issue: the property has been at stabilized occupancy for years and the assessment history has been relatively consistent. It’s when the property is proposed or being repositioned that it becomes trickier, or when the assessment simply doesn’t make sense.

According to the NYC Dept. of Finance assessment guidelines, all property is reassessed annually at 45% of market value. However, the assessor’s estimate of market value can be dramatically different than an appraiser’s, for a couple of reasons: (1) the assessors are given guidelines on what cap rates to use based on the band of investment and (2) the cap rate is then “built up” by the effective tax rate and applied to NOI before real estate taxes are deducted, (3) the cap rate is applied to the most recent income submitted to DOF, usually a year old by the time of the tax year, (4) because owners are submitting the data for taxation purposes it is often understated.

For example, according to Finance, the cap rate for a Manhattan apartment building should be between 8.2% and 12.2%, depending on the level of income generated. Notwithstanding the fact that these cap rates make no sense relative to true market cap rates, should the appraiser simply disregard the taxes in place and calculate taxes based on these rates? Or should taxes simply be estimated based on 18% to 22% of EGI? Doing either of these may result in substantial increases (or declines) in taxes from current levels.

Throw in other variables like the “8%-30%” limitation rule and the spreads between transitional and actual assessments, and you can see why understanding where real estate taxes are going for a property in NYC is especially challenging. More of this in future posts…

Condo developers throughout the City are no doubt reeling over a recent court ruling that makes it much easier for a buyer to rescind its contract in a new development. In an article in today’s Wall Street Journal, Buyer’s Remorse Gets Lift, Josh Barbanel reports on a Judge Kevin Castel’s ruling in a case involving the Related Company’s building on the Upper East Side, the Brompton. By citing an obscure 40-year old law, the Interstate Land Sales Full Disclosure Act, a buyer at the Brompton sued to get his deposit back. This law, originally dealing with land subdivisions in Florida, was interpreted to extend to condo developments in Manhattan as well.

Buyers throughout the City will no doubt see this as a green light to try and get their deposits back on apartments that they now feel are overpriced, but had little leverage to do anything about it. Developers will inevitably be less inclined to play hardball, and either return the deposit or renegotiate the price.

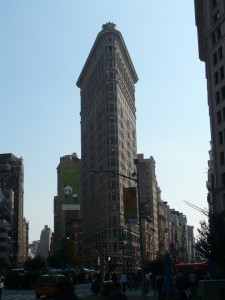
One of my favorite buildings in NYC is the Flatiron Building, a triangular shaped building on 23rd Street, where Fifth Avenue and Broadway intersect (175 Fifth Avenue). Built in 1902, it was originally called The Fuller Building. I had always thought that it was the first steel-framed skyscraper in NYC, but the AIA Guide to New York City corrected me (that was apparently a building on Park Row).

P1000525

It’s a striking building at the south end of Madison Square Park that looms as you walk down either Fifth or Broadway. According to the AIA Guide,

Here rusticated limestone is uniformly detailed from ground to sky, in the manner of an elevatored palazzo. The acutely angled corners give it an exagerrated and dramatic perspective

Besides just being a cool-looking building, it has sentimental meaning…nearly 35 years ago my first job out of college was in that building and after a couple of years I worked my way up to a tiny office that was at the very point of the building….could barely fit a desk but those views up Fifth Avenue and Broadway were the start of my love affair with this city.

There’s a new one to add to New York City’s alphabet soup of real estate terms. Now, along with the RPIE, ICIP, BOMA, SCRIE, J51 and a slew of others, there is the DBB-N, or the “Notice to Tenant: Disclosure of Bedbug Infestation” history. In today’s Wall Street Journal article, Bedbug Disclosure Required, Josh Barbanel reports on the new requirement, signed into law by Governor Paterson several weeks ago. The bill requires that landlords disclose to all new tenants in writing whether a bedbug infestation has been found in the apartment (or building) over the past year.

I take solace that while I sit here in my midtown office, New York City is ranked only 7th in the nation for for bedbugs; the Gothamist reports that Cincinnati, Ohio is #1. I start scratching just thinking about this.

Exciting day around here. Today we announced the formation of our new company, MillerQA. Together with Jonathan Miller, Cheryl Miller, Dina Miller and Karen van DerVrande, MillerQA was formed to “foster market understanding” by creating seminars on the state of the housing market. My friend, partner and housing guru Jonathan Miller will present the third quarter 2010 housing results from his quarterly analysis of the market (as reported in the Prudential Douglas Elliman Market Overview). The seminars will be geared towards professionals-such as attorneys, accountants and of course real estate brokers-who touch on real estate in their day to day lives, though we expect that many buyers, sellers and investors will also want to attend. (Applications are pending for continuing education credit for attorneys, accountants and real estate brokers.)

The seminar will be interactive by incorporating i>clicker technology, an audience response polling system.

Our first seminar is scheduled for the Scandinavia House (58 Park Avenue, New York, NY) on October 7, 2010 from 4:00 to 7:15 pm. Steve Wagner, an attorney specializing in housing transactions will be the featured guest speaker. (To register click here.) The seminar will also be available online.

I’ve been a Member of the Appraisal Institute since 1990. At the time the MAI designation was highly-coveted and well-respected (before some snarky investment banker coined the term “Made As Instructed!). Over the past two decades, however, the Appraisal Institute has been struggling to maintain its voice and its role as the pre-eminent appraisal organization. First a little history:

After the Savings & Loan crisis in the late 1980’s Congress passed the Financial Institution Reform, Recovery and Enforcement Act (FIRREA) in 1989. One of the mandates of FIRREA to create an Appraisal Foundation that was to be comprised of the an Appraisal Standards Board (ASB), which would develop the Uniform Standards of Professional AppraisalPractice (USPAP) and the Appraiser Qualifications Board (AQB) that would develop the standards for state licensing of appraisers. With the advent of state licensing the MAI designation began to dilute as any state licensed appraiser could now call himself a professional appraiser.

The Appraisal Foundation has been the primary organization driving appraisal standards for the past twenty years. It is made up of nine sponsor organizations, including the Appraisal Institute, and is intended to represent all professional appraisers with a single voice.

Over the past few months there has been a lot of vitriol between the Appraisal Institute and the Appraisal Foundation. From what I can understand (and it’s not easy to piece this together with all the “spin”), the controversy goes something like this: During the negotiations for the recent Financial Reform Bill in Congress, Appraisal Institute lobbyists did an end-run around the Appraisal Foundation and has discussions with members of Congress on its own behalf. Incensed, the Appraisal Foundation suspended the Appraisal Institute for a period of seven months. From there it turned into blame game of he said/she said pointing the finger at the other and attempting to stake out the higher ground. The Appraisal Institute reluctantly appealed to the Appraisal Foundation to reverse its decision; while the decision was not reversed the suspension was reduced to three and a half months.

Which brings us to the present. Leslie Sellers, current national president of the Appraisal Institute reported to its membership yetsreday that

we could not ethically and in good conscience have the Appraisal Institute accept punishment for something the Appraisal Institute did not do..accordingly, we, as your Board of Directors, have informed the Foundation that the Appraisal Institute has chosen to withdraw the Appraisal Institute’s sponsorship of the Foundation

To which I say, Are they out of their minds!!!??? This has evolved to our national leadership acting like a bunch of kids in the sandbox, and can only hurt all members of the Appraisal Institute..bringing the MAI designation one step closer to irrelevancy. I suspect that there will be a huge backlash from its members in response to the leadership’s position, so who knows how this will actually end up. The fact that the AI Board would take such a step without first polling its members is incredible.

Aren’t appraisal politics fascinating? My partner, Jonathan Miller, has written on the subject in his Matrix blog, and even added video (which I have not yet learned how to do).
  • Categories

  • Tags