Archive for February, 2010

We’re out and about the streets of New York all the time, and every so often something interesting catches our eye…

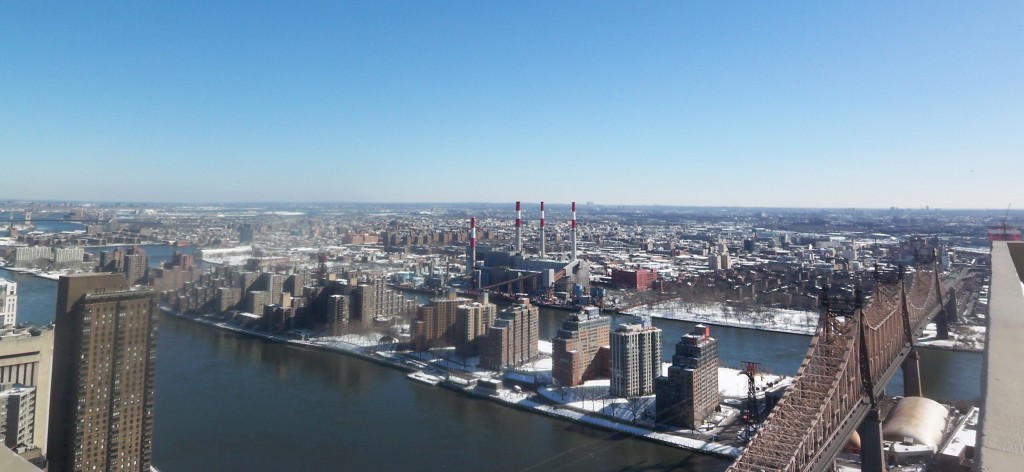
The view from the top of the Sovereign, a luxury co-op building on East 58th Street, as taken by our resident hipster, Tyler King. Built in the 1970’s, it was for a while the tallest residential building in the City.

Sometimes we forget that Roosevelt Island is, well, an island! From 47 stories up, looks like a pretty cool island, at that!

100_5633

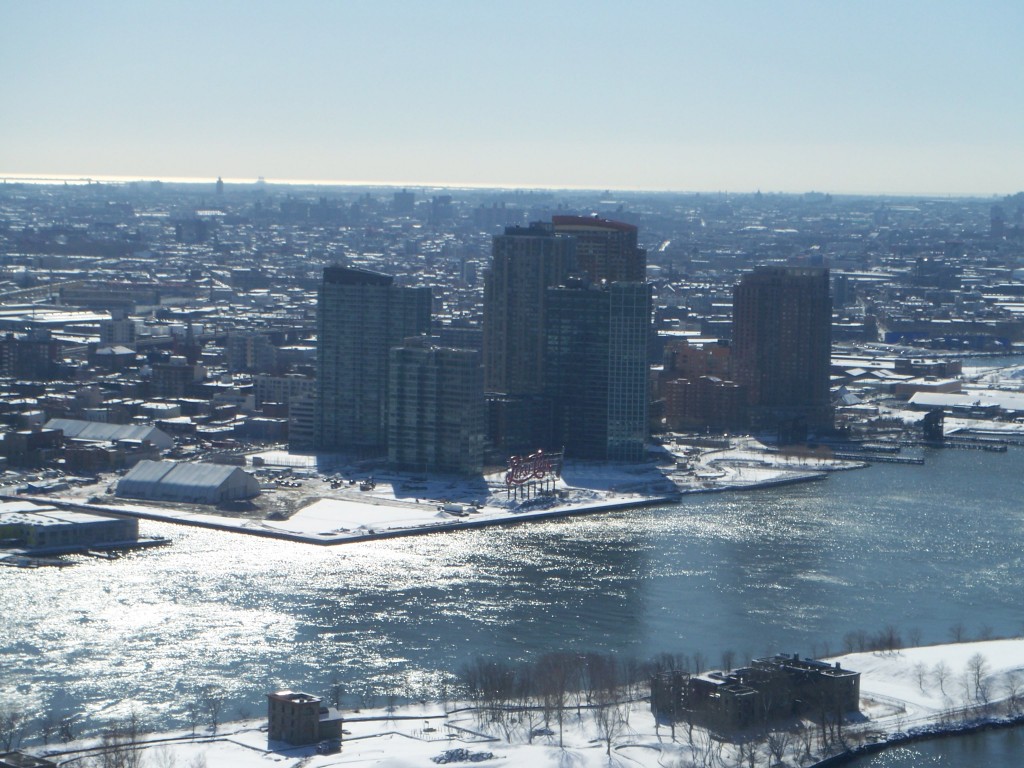
Another view east of the East Coast Towers in LIC with the legendary (and landmarked) Pepsi Co sign in the front.

100_5634

Appraisers are by their very nature data hounds. That’s why we get so excited when The Real Deal comes out with their annual Data Book. The 2010 Dat Book was just released…163 pages of pure real estate data bliss! The median price of a home in Gravesend Brooklyn in 2009? $420,000 (up 9.8% from the prior year). Want to know the number of stalled condo projects in Western Queens? No problem…133. The biggest office lease in 2009? Yep, it’s in there…82,551+ square feet to Holland & Knight. And, of course, there are pages and pages of stats from our residential affiliate, Miller Samuel Inc, author of the must-read Prudential Douglas Elliman Market Overviews.

We love data. We especially love when it comes delivered right to our office!

by Tyler King, Resident Hipster

Although we here at Miller Cicero, LLC are a commercial real estate advisory firm, we share offices with the residential firm Miller Samuel Inc. So, I am in the loop when it comes to all issues surrounding residential appraisal and today I stumbled upon a very interesting article from the Appraisal Institute that directly relates to the residential appraisal business.

In response to the recent credit implosion there is a whole slew of new guidelines that have been adopted by federal agencies to help prevent collusion, undue influence, and fraud between mortgage brokers, banks and appraisers (these guidelines are collectively known as HVCC). Without going into specifics, let’s just say that the guidelines mean well, but in realty, often do more harm than good (a great article can be found here). Essentially, the new guidelines are perpetuating an army of mindless form-fillers that are suppressing both fees and turnaround times. In other words, life is tough for the residential appraiser right now.

So what is an appraiser to do? Stop doing appraisals of course! Enter the good folks over at First American Valuation and Property Solutions who have introduced the “Appraiser-Validated Price Opinion”, or AVPO. If it is not an appraisal then it is not subject to USPAP and HVCC standards. Looks like this is how you compete with the churn-and-burn residential appraisal factories.

Here is how I understand an AVPO works: basically, a licensed appraiser checks the value of a property as previously determined by a local real estate agent. To do this, the appraiser looks at comparable sales and determines if the broker is indeed correct. If the appraiser is of the opinion that the broker is mistaken in his/her value, the appraiser assembles the comps and provides a new value. With this new value, information on the rationale of how the value was determined is included (i.e. an explanation of adjustments).

So to recap: The (licensed) appraiser looks at a set of comps, from these comps logical adjustments are made, and the appraiser formulates a value opinion. Yes…I see…that sounds nothing like an appraisal.

In this month’s Real Deal magazine Sarah Ryley’s Stalled Projects Come Back From the Dead looks at 20 stalled projects and reports on their strategy for coping with the downturn. The answer for a good number of the projects is the return of the “taxpayer.” You may remember, in the old days that’s what we used to call those single-story retail strips that would throw off enough income to pay the property’s real estate taxes, temporarily, until the site could be developed. In appraisal-speak, we call it an “interim highest and best use” and could be any temporary use until market conditions render new development feasible.

At 304 Fifth Avenue, for example, developer The Wings Group is opting to build a single-story retail building on the site, since it couldn’t get financing for the planned 14-story tower. The $400,000 that they project in rental income should be more than adequate to cover taxes. A number of other sites (e.g. 677 11th Avenue, 86-98 Canal Street, 510 Driggs) are planning on operating as surface parking lots. When you get right down to it, with the perpetual need for parking in this City, how can you ever go wrong buying a development site.

by Tyler King, Resident Hipster

I have decided I am going to bid above ask on a new condo in a secondary location, Brooklyn preferably, in a building that is only 4% sold after a year of marketing and is not expected to be finished until the Fall of 2010 (at least that is what the broker says). They just poured the foundation and man do the floorplans look nice! According to the brochure, I will get Toto toilets, a soaking tub (as opposed to the standing room only tub I currently have), and heated towel racks. Oh, and I decide to splurge and buy a $75,000 parking space along with the unit were I can park the brand new Toyoto I just purchased. I know that people are worried about Toyota’s little accelerator pedal problem, but I have no problem with a faulty gas pedal, I like to go fast.

Wait a second, that is the mid-2007 me talking. Boy do I sound dumb! Things no longer work this way. People are thinking rationally about purchases, and are not blowing their money on the next gimmick (pet spas?). However, people are making purchases. Units are selling. Even in the unsure world of new development. Just the other day I saw an unconfirmed tweet from The Real Deal chirping that at The Oro sales have picked up to 10 – 20 units a month. And get this, The Forte is now reportedly 100% in contract. This, after a stiff cocktail of bankruptcy and price-cutting. What does this mean? Prices in new development is coming down (or maybe plummeting is a better word) to a point where buyers are now willing to pull the trigger and buy something. The bid/ask gap is beginning to close, with most of the give coming from sponsors.

So for 2010 I foresee some projects selling steadily. I predict the word of the year is going to be variations on “stable”. Stabilizing, stabled, stableness, stably, etc. (I hope this works out better then when I predicted 2009 to go down in history as the year of the land sale). According to the Fourth Quarter 2009 Prudential Douglas Elliman Brooklyn Market Overview (prepared by Miller Samuel Inc., an affiliate of Miller Cicero, LLC), in the North Brooklyn submarket, condos are averaging $564 per square foot, down from a year ago. At the same time the report is seeing increased sales activity as listing inventory is declining market wide. Translation: Things might just be stabilizing. See, there’s that word again.

I’m in the middle of reading Michael Pollan’s book, In Defense of Food, in which he lays out a clear common sense approach for getting back to basics when it comes to food and eating. He argues that all the scientific research has confused everyone to the point that nobody knows what to eat anymore, and sums up his findings for healthy and enjoyable eating with the following words: “Eat Food. Not Too Much. Mostly Plants.”

The parallels with real estate are obvious (aren’t they?). What was once a fairly simple investment or home purchase had become muddled with the advent of the ever-improving structured finance vehicles coming out of Wall Street. Many buyers didn’t really understand the whole system, but just a small part of it. Every real estate purchase was based on the newest “science” coming from the financial “scientists.” At the end of the day, however, it’s clear that Pollan’s back to basics approach holds true for real estate as well: “Buy Real Estate. Good Property. Don’t Overleverage.”

by James Dunne - The CREative Department

This is the second in a series of blog-posts about the costs incurred in running a multi-family building. Last week I wrote about management companies that run buildings and the fees they charge. In this post I will cover the people actually keeping a building running: the building superintendents. Supers typically fall into one of two categories: onsite or offsite. Onsite supers usually live in an apartment in the building, typically provided as part of their compensation, and are expected to be available 24/7 in case of an emergency. Like the cost of hiring a management company, the salary a super is paid can vary wildly. In a small building, with say 12 units, a super might have an apartment provided to them free of charge (typically in the basement or ground floor), but may only get paid a small fee, which could be as low as $100 per week. In this scenario, a couple often shares the super’s activities, with one spouse or significant other working, while one stays home to mind the building.

In mid-size buildings, with say 50 or 60 units, a super’s duties will be greater. A super in a building of this size can expect a salary of about $30,000 plus their apartment provided to them; however, the larger the building, the greater the responsibility. At the top of the pay range, a super in a luxury building with 400 units may have a salary as high as $80,000 per year, or more. Of course, this super will be managing a staff, as large as 20 people, including porters, maintenance people, maids and doormen.

However, for many small buildings, on onsite super is usually not needed. Small buildings typically have an offsite or “visiting” super, which is usually just a cleaning person who may also perform light maintenance. At the low end of the fee range, a building may pay this super $300 per month to handle simple duties such as taking out recycling, garbage, and cleaning the common areas. This could be a neighborhood person who cleans a few buildings. However, as one building manager told me “you get what you pay for.” A building owner can expect to pay $700 to $800 per month for a good visiting super, which is usually provided through a building maintenance company. A good visiting super will be pro-active about identifying and solving building maintenance problems before they lead to more serious problems. For the $700 - $800, a building owner typically gets a visiting super for 10 to 12 hours a week. But like management fees, the cost of a visiting super can be negotiated. Often, management companies also run building maintenance companies, and will push their own company to handle a building’s cleaning and maintenance, but in long run, a building owner will save money by having someone knowledgeable and responsible taking care of their building.
by Gleb Lerman, The Affordable Oracle

Affordable housing is all over the news, especially in NYC. In a series of blog posts I will cover some of the stuff I learned over the last five years of appraising and consulting on affordable housing in NYC. Most of my posts will focus on the development and operations of affordable housing.

One of the main reasons for building affordable housing is the subsidies that are available. In return for these subsidies (to be covered in later posts) a developer encumbers the property with restrictions. The restrictions consist of income restrictions and rent restrictions.

An income restriction sets the upper limit of how much money a tenant or household can earn and still be eligible for the housing. The programs as well as the regulatory agreements encumbering the properties specify that the income limits be based Area Median Income (AMI) published annually by HUD. HUD publishes AMI numbers for multiple geographic regions (however all of NYC falls into one AMI area). Most affordable housing programs target certain populations (extremely low income, very-low income, low income, median income) which are defined as percentages of the published AMI numbers. Here are the 2009 AMI limits for NYC taken from huduser.org.

Screen 001

Illustration: Lets say the Smiths want to live in 125 Main Street developed under an affordable housing program which is targeted to the Very Low Income Population (50% AMI). The Smith household consists of a five people and their gross annual income is $39,250. To see if the Smiths are eligible for housing in 125 Main Street we look to see what the Very Low Income limit for a 5 person household is. It’s $41,450. The Smiths are in fact eligible and can thus apply for housing at 125 Main Street.

Many programs, especially in NYC don’t fall into the 30%, 50% or 80% AMI categories illustrated above. Some programs have 60% income limits, some have 120% income limits and some have 175% income limits. However some basic arithmetic can go a long way. If 50% AMI for a household of 2 persons is $30,700 then 100% AMI for a household of 2 persons must be $61,400. You can test your understanding by looking at various affordable housing applications on HPD’s website (and seeing if you can figure out what income limits are set for each unit. Hint, in some cases not all the units in a building have the same AMI restrictions.) Fascinating stuff, eh?

Coming soon! Rent restrictions, Subsidies, some recently completed affordable housing projects, Low Income Housing Tax Credits, the development budget, 4% vs 9% tax credits, and eligible basis…

  • Categories

  • Tags